 By
Drivers moving from a petrol car to an electric one often expect insurance to work the same way with a different vehicle attached, and then find the renewal quote behaves differently from what their driving history would suggest. The reason is that several of the inputs insurers price against change with the drivetrain. Repair pathways differ, the most expensive single component is different, and the equipment attached to the vehicle extends beyond the car itself. Four differences explain most of the gap between EV insurance in Singapore and a comparable petrol policy, and understanding them makes a quote considerably easier to interpret.
1. The Battery Is the Dominant Repair Cost Consideration
In a petrol car, the most expensive components are distributed across an engine and gearbox that can often be repaired in parts. In an electric vehicle, the traction battery represents a large share of the vehicle’s value and is frequently replaced rather than repaired.
That changes the loss calculation on a moderate collision. Damage that would be an ordinary repair on a petrol car can approach a write-off threshold on an EV if the battery pack is affected, and insurers price for that. It is worth asking specifically how a policy treats battery damage, whether replacement is at full value or depreciated, and whether the battery is covered if it is leased rather than owned.
2. Repair Networks and Parts Availability Are Narrower
Electric vehicles require technicians with specific training and workshops with appropriate equipment, and the network of approved repairers is smaller than for petrol vehicles.
That affects both cost and repair duration. Anyone comparing car insurance in Singapore across drivetrains should check which workshops a policy authorises, whether manufacturer-approved repair is included, and what courtesy vehicle provision applies given that repairs may take longer than the equivalent petrol job.
3. Charging Equipment and Cables Need Explicit Cover
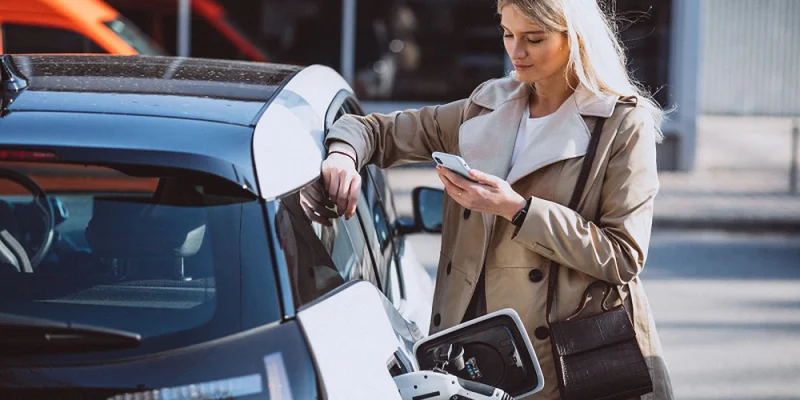
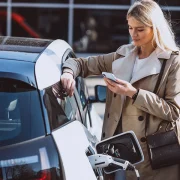
An EV comes with equipment that has no petrol equivalent: a home charging unit, portable cables, and adaptors. These are frequently stolen or damaged, and whether they are covered depends on the policy wording.
Check whether a wall-mounted home charger is covered under the motor policy or expected to sit under home insurance, whether cables are covered when in use at a public charger, and what limit applies. Policies differ meaningfully here, and the gap is easy to miss when comparing headline premiums.
4. Usage Patterns and Risk Profile Are Assessed Differently
Insurers consider how a vehicle is used, and EV ownership patterns differ in ways that affect pricing. Performance characteristics, typical mileage, where the vehicle charges, and the owner profile all feed into assessment.
Some insurers also account for incidents specific to electric vehicles, including damage sustained while charging and the handling of a damaged battery, which carries its own procedures.
Comparing Quotes on the Right Basis
The practical approach is to stop comparing premiums alone and compare what each policy covers for the components that matter on an EV. Ask each insurer the same questions: how battery damage is assessed and settled, which repairers are authorised, whether charging equipment is included and to what limit, and what happens if a repair takes an extended period.
Quotes compared that way often rank differently from how they rank on price, and the cheapest premium sometimes turns out to carry the narrowest battery provision. What applies to your situation depends on the specific vehicle, how it is financed, whether the battery is owned or leased, and how you use it, which makes a direct conversation with an insurer describing your actual arrangement more useful than a general comparison.
Contact Income Insurance to discuss how your electric vehicle’s battery, charging setup, and usage would be assessed for cover.


Comments